Virginia Crash Claims Guide
Trucking Adjuster Recorded Statement: What to Know Before You Speak
After a truck crash, an insurance adjuster may ask to record your account. Learn who the adjuster works for and what a recorded statement can mean for your claim.
Published October 28, 2026
A recorded statement to a trucking company’s insurance adjuster is a request many injured people receive early in a claim. The adjuster works for the insurance company, not for you. You may wish to think carefully before you answer. This guide explains who the adjuster represents, how a recording can be used later, and what to do before you speak. It is general information about Virginia law, not advice on any one claim.
What Is an Insurance Adjuster?
An insurance adjuster is the person who investigates and values a claim for the insurance company that employs or hires them. The adjuster’s job is to protect the insurer’s interests in the claim, which is a different goal from yours.
When a commercial truck is involved, the trucking company’s insurer often assigns its own adjuster. That call can come within days of a crash. Some injuries take time to show their full effects, so an early call may come before you know the extent of your injuries. That timing is why the first call matters.
For the wider picture of commercial vehicle claims in Virginia, see the commercial vehicle accident guide.
If a trucking company's adjuster has contacted you after a crash, the firm is glad to talk through your situation so you don't have to face it alone. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
What Is a Recorded Statement and How Can Adjusters Use It?
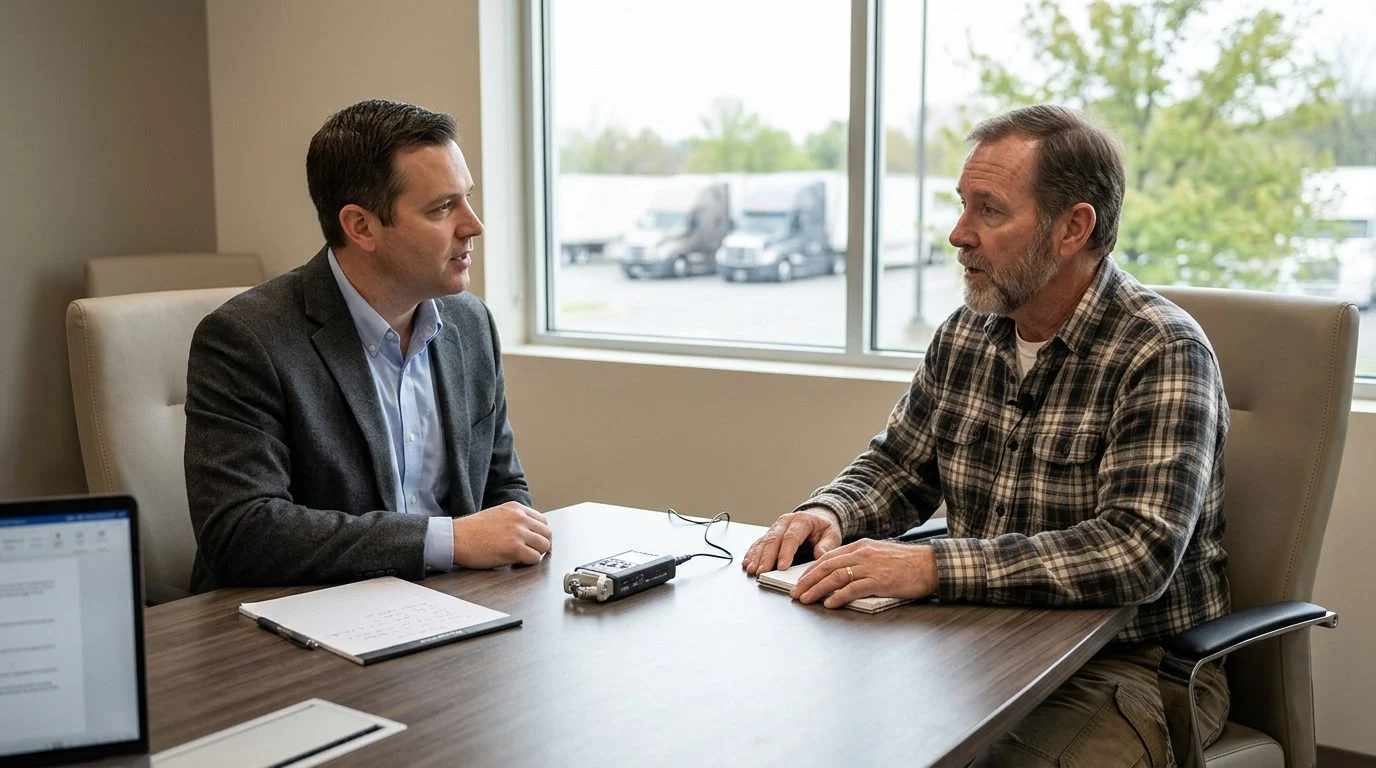
A recorded statement is a spoken account of the crash, your injuries and related background. It is captured on audio or digital recording. The insurer uses it to lock in your account of events early in the claim.
Later, the adjuster may compare that account with the police report, medical records, photos and statements from other people. Any difference can be used to dispute the claim. Small details matter. A guessed speed, a rough distance or the words “I’m fine” can be quoted back later, even if you offered them only as an estimate.
Adjusters also ask broad questions about your past health. A quick answer given without checking can look incomplete later. Once a statement is on record, it can be hard to correct.
Should I Give a Recorded Statement to an Insurance Company?
Whether to give a recorded statement depends on the facts of the crash, your injuries and who is asking. It helps to see the full picture first.
You may wish to speak with a lawyer before giving a recorded statement, especially if your injuries are serious or still being diagnosed. A lawyer can explain how a recording may be used in your situation.
Start by asking the adjuster for their name, the insurer’s name, the claim number and the reason for the recording. Ask for the request in writing so you have a record of it. You can also say you need time to review your notes before you answer.
What Not to Tell an Insurance Adjuster
Stick to what you remember, and say when you are not sure of a detail. Avoid guessing about speed, distance, time of day or road conditions. A guess can become a fact in someone else’s file.
Do not describe your injuries as minor. Do not say you are fully recovered before a medical provider has evaluated you. Describe your symptoms as you feel them today, and say if treatment is ongoing.
When fault comes up, do not speculate about who caused the crash, and do not accept blame. Virginia follows contributory negligence: if you are found even partly at fault, you may be barred from recovering, with limited exceptions. Talk to a lawyer about your facts.
Avoid posting about the crash, your injuries or your activities on social media while a claim is open. Insurers may review public posts.
Evidence and Records to Keep in View After a Truck Crash
Trucking companies keep records that can shape a claim, and some of those records are kept for only a set time. Knowing which records exist helps you understand what the adjuster may already have.
Federal rules require motor carriers to record each driver’s duty status for each 24-hour period. Carriers operating commercial motor vehicles must use an electronic logging device, with listed exceptions (49 C.F.R. § 395.8). Driving time is also limited. A driver of a property-carrying commercial motor vehicle may not drive once more than 8 hours of driving time have passed without at least a consecutive 30-minute interruption, except for drivers who qualify for certain short-haul exceptions (49 C.F.R. § 395.3). For more on these rules, see the hours-of-service guide.
Retention periods matter too. Companies subject to this federal rule must keep records for minimum retention periods set in its appendix; after those periods, the records may be destroyed at management’s discretion, unless another governmental body prescribes longer retention periods (49 C.F.R. § 379.3). Some evidence can be lost over time, which is why it helps to learn what exists early. See the evidence guide.
Highway crashes on Interstate 81 in the Shenandoah Valley, including tanker truck crashes, can raise different questions about records and cargo. See the tanker truck crash guide.
Deadlines That Run Alongside an Insurance Claim
A lawsuit deadline runs on its own clock, separate from any insurance claim. Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions.
It is not the deadline for reporting a crash.
Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894).
Keep the lawsuit deadline in mind even while an insurer is still reviewing your claim.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Preparing Before Any Call From the Insurer
Keep a written record of every call, letter and email before you speak on the record. Write down the date, time, caller’s name, company and claim number for each call. Keep copies of all letters and emails from the insurer.
Keep a log of medical visits, treatment, prescriptions, missed work, bills and receipts. These records often shape what an adjuster asks about next.
Gather the police report number, witness names, and any photos or notes from the scene. That way, details are not rebuilt from memory.
Before any recording starts, confirm who the adjuster works for, which claim is under review and why a recording is requested. Then confirm you understand each question before you answer it.
Quick Answers
Should I give a recorded statement to a trucking company insurance adjuster?
It depends on the facts, and you may wish to speak with a lawyer first.
Does an insurance adjuster work for me?
No. An adjuster works for the insurance company that employs or hires them.
Can a recorded statement be used against me?
It can be, if details are guessed, incomplete or do not match other records.