Car and Truck Accidents | Virginia
Not at Fault? Think Carefully Before You File an Insurance Claim
A plain-language guide for Virginia drivers, from the Shenandoah Valley to Richmond, on reporting a crash, dealing with insurers and knowing when to ask for help.
Where the firm works
Winchester
Office
Harrisonburg
Office
Virginia
Crash and injury cases statewide
Published October 26, 2026
Should I file an insurance claim if I am not at fault? Often, yes. The answer depends on your policy, the facts, and whether anyone was hurt.
Being hit by someone else’s mistake is frightening. You may be sore, shaken, or trying to reach family. This guide explains the basic choices in plain words. It is general information, not advice about your own case.
Why This Question Comes Up After a Crash You Did Not Cause
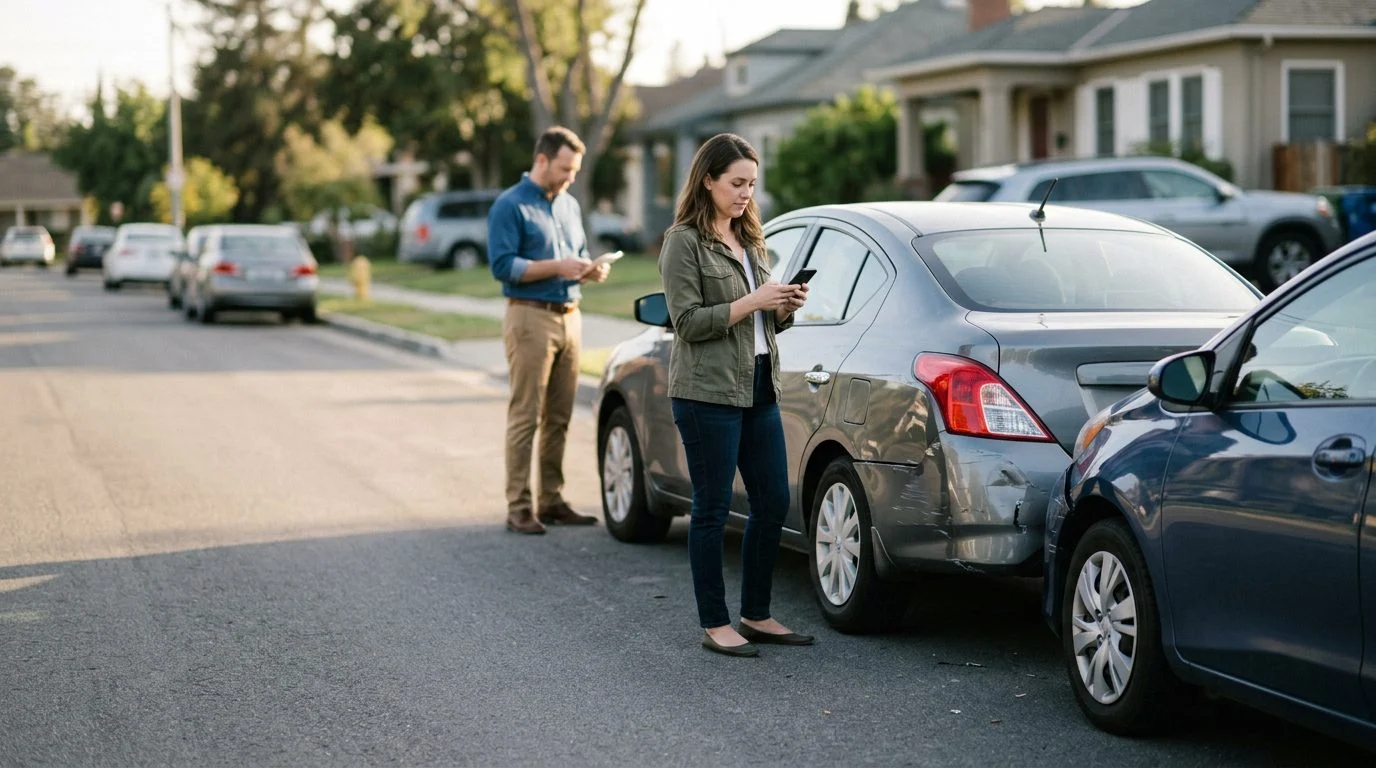
Many readers ask whether they should file an insurance claim if they are not at fault. The crash was not their doing, so it seems the other driver’s insurer should handle everything. That idea is only partly right. Fault matters, but so do the policies involved, the injuries, and how each claim is opened.
Most people face four separate decisions. The first is whether to report the crash to police. The second is whether to contact their own insurer. The third is whether to deal with the other driver’s insurer. The fourth is how to handle calls from any adjuster.
Each decision has its own rules, so this page takes them in order. Your policy language and your facts shape what happens next.
If you were hurt in a crash you did not cause, you may have a claim, and the firm is glad to talk through your situation with you. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Start With the Crash Report
Report the crash to police first, even if you believe you did nothing wrong. Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894).
A police report is a written record. It can list the date, time, and place, the vehicles, the drivers, and what the officer observed. Write down the report number and the officer’s name. Keep them with your photos and notes.
Your Own Insurer Versus the Other Driver’s Insurer
A driver who was not at fault may deal with their own insurer, the other driver’s insurer, or both. Which path fits depends on your coverage and the crash.
Your policy’s declarations page lists your vehicles, your coverages, your limits, and your policy number. Read it before you reach out. Common coverage names include collision, medical payments, and uninsured motorist coverage. Each name covers something different, so the names on your page matter most.
Virginia’s rules for uninsured and underinsured motorist coverage appear in Va. Code § 38.2-2206. Read that statute alongside your own policy, not instead of it.
The other driver’s insurer works for its own insured. Its adjuster may ask for a recorded statement or make an early offer. Put any requests and offers in writing so you have a clear record.
How Fault Still Matters Even When You Were Not the Driver Who Caused the Crash
Virginia follows contributory negligence: if you are found even partly at fault, you may be barred from recovering, with limited exceptions. Talk to a lawyer about your facts.
This is why a casual remark can matter. A statement such as “I think I may have been going a little fast” can be repeated and used later. Treat every statement to an insurer as one that could be shared.
Do not guess about fault to be helpful. Say what you saw, and say when you are not sure about the rest.
What to Say and What to Avoid When Insurers Call
Stick to facts you saw yourself. These include the time, the place, the weather, the vehicles involved, and who was hurt.
Avoid speculating about speed, fault, or injuries that a medical provider has not yet checked. A quick “I’m fine” on a call may not match how you feel a few days later.
Write down the adjuster’s name, the company, the claim number, and the date and time of each call. Keep a short summary of what was said. Save every letter and email.
If you do not know an answer, say you do not know yet. A clear “I don’t know yet” is safer than a guess made under stress.
What Changes in Truck and Commercial Vehicle Crashes
A crash with a commercial truck often involves more parties and more insurers than a car crash. The truck’s size is one reason.
More parties can mean the truck driver’s insurer, the trucking company’s insurer, and sometimes a separate owner or carrier. Federal rules require a motor carrier to have minimum financial responsibility before it operates. Under 49 C.F.R. § 387.7, that proof must be kept at the carrier’s principal place of business. It is public information that can be produced on reasonable request.
If you can, write down the carrier’s name and the truck’s number. Keep your photos of the truck and the trailer.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Medical Care and Keeping Records
Get checked by a medical provider after any crash, even for a symptom that seems minor. Some injuries are hard to spot at the scene.
The National Institute of Neurological Disorders and Stroke provides information on traumatic brain injury, including its causes. Tell every provider about each symptom, including headaches, dizziness, or confusion.
Keep every bill, receipt, and visit summary. Keep notes about missed work and any wage records. A simple daily journal of symptoms, with dates, can help you recall details later.
Keep copies of everything you send to or receive from any insurer. Which losses can be recovered depends on the facts.
When It May Be Worth Talking Through Your Situation
You may wish to talk with a lawyer when injuries are serious, a commercial vehicle is involved, fault is disputed, or an insurer has denied or delayed a claim. A lawyer can review your policy, the crash report, your medical records, and the insurer’s letters with you.
The firm represents people hurt in car and truck crashes, and families in wrongful death cases, from the Shenandoah Valley to Richmond and Henrico County.
Should I file an insurance claim if I am not at fault?
Often, yes, but your policy and the facts decide what comes next. Reporting the crash and notifying your own insurer are common first steps.
What is a recorded statement?
It is an account an insurer asks you to give, often by phone or in writing.
Who files a wrongful death action in Virginia?
A Virginia wrongful death action is filed by the decedent’s personal representative within two years of the death (Va. Code §§ 8.01-50(C), 8.01-244(B)), on behalf of the family members the statute protects.