Car Accidents | Virginia
Car Accident Claim Adjuster Timeline in Virginia: What Shapes the Pace
Insurance claims after a crash rarely move on a fixed schedule. Here is how the adjuster's process usually unfolds and what can speed it up or slow it down.
Published November 2, 2026
This page explains the car accident claim adjuster timeline Virginia drivers and passengers usually face. There is no fixed length. How long an adjuster takes depends on the facts, and most of all on how much medical information the file holds. This guide covers what sets that pace, where the paperwork starts, and which legal deadlines run on a separate clock. It is written for people across the Shenandoah Valley, Richmond and Henrico County who are waiting on a claim.
How long do insurance adjusters typically take to evaluate and respond to a car accident injury claim in Virginia?
The time depends on the facts, especially how complete the medical picture is.
Claims tend to move faster when fault is clear and treatment is finished. The adjuster can see the injury’s full scope and the bills that come with it. When records are still arriving or the injured person is still treating, the review often slows.
A quick reply and a fair evaluation are not the same thing. An early response may rest on partial information. Adjusters work from what has been documented so far.
Keep two timelines apart. The adjuster’s review is one schedule. The lawsuit deadline comes from statute. The firm’s guide to the full Virginia car accident claim process explains how the two fit together.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
What happens in the first days after a Virginia car accident is reported?
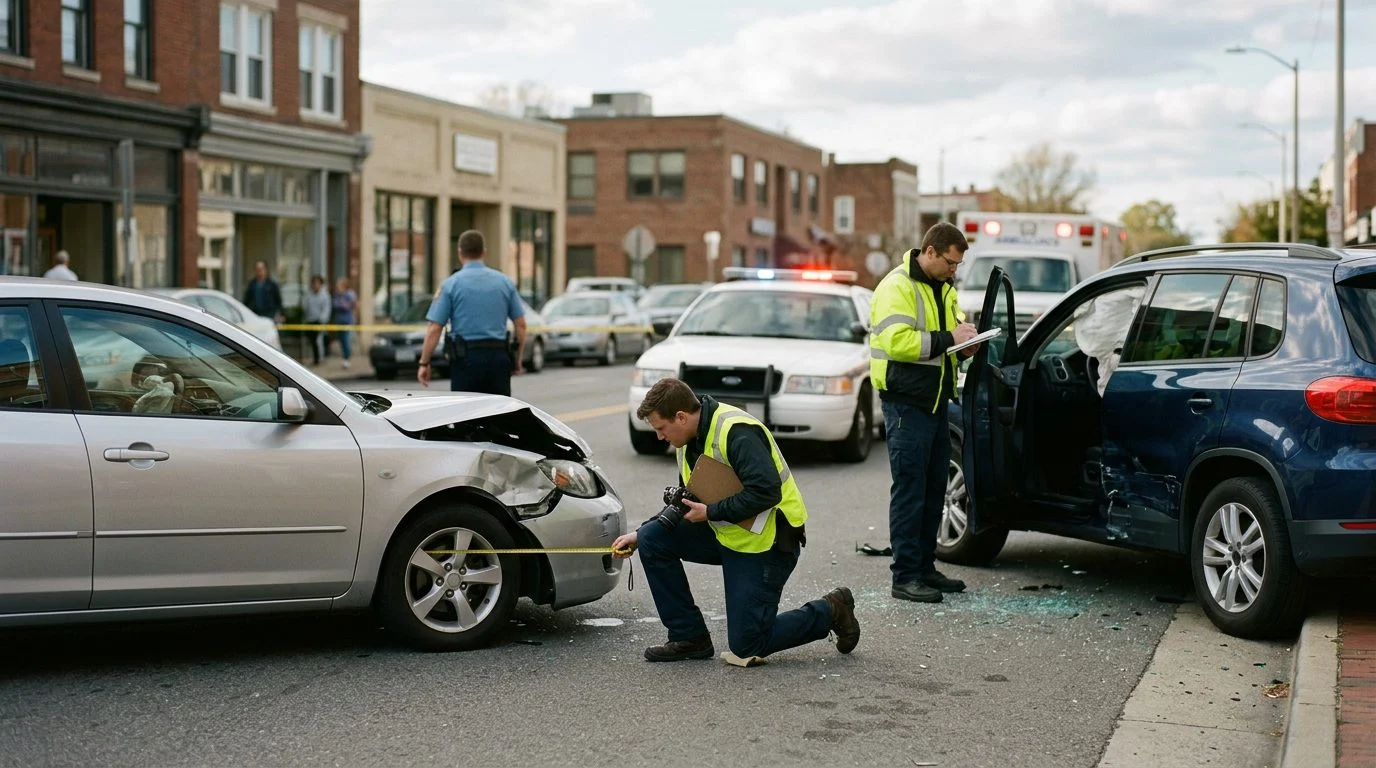
The first days usually focus on the crash report, photos and early statements. Those items form the first file an adjuster opens.
Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894). The duty appears in § 46.2-371 and § 46.2-894.
That reporting duty is separate from any insurance claim. The two-year period discussed below is the deadline to file a lawsuit, not the deadline to report a crash (Va. Code § 8.01-243).
Opening a claim is not the same as the insurer accepting fault or agreeing to cover the loss. An insurer may open a file while it is still deciding who is responsible. Keep copies of everything you send and receive.
Why does medical treatment often set the pace of an adjuster’s evaluation?
Adjusters usually need treatment records, bills and provider notes before they can judge an injury’s full scope.
Some crash injuries, especially to the head, neck or back, take time to show their full effect. Symptoms can change over weeks. A doctor may not know the long-term picture until treatment has run its course.
A claim judged before treatment ends may rest on incomplete information. That can lead to a slower review, a request for more records, or a reply that changes as new medical facts arrive.
Organized records help the file move. Appointment notes, prescriptions and bills all add to the picture. Missing records leave gaps that take time to fill.
How can a claim with more than one injured person change the timeline?
More injured people usually means more files, more insurers and more records. The review often takes longer as a result.
A passenger’s claim may involve the driver’s insurer, the passenger’s own coverage and any other party whose conduct played a part. Each insurer may request its own records and run its own review.
Each injured person’s records and treatment run on their own schedule. One file can close while another stays open.
How does the Virginia filing deadline differ from the adjuster’s timeline?
The lawsuit deadline runs on its own clock, set by statute. It does not depend on how fast an adjuster responds.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions. The accrual rule appears in § 8.01-230, and the deadline appears in § 8.01-243.
A pending insurance claim does not change the date of injury.
Some claims carry shorter notice requirements. The adjuster’s pace should never be treated as the controlling schedule.
How do the stages of a Virginia car accident injury claim fit together?
The stages run in order but overlap. A delay in one stage usually slows the next.
A typical claim moves through five steps: reporting the crash, opening the claim, gathering records, the adjuster’s evaluation, and the response to the injured person. A property-damage question can run on a different track from the injury claim. A Highway Loss Data Institute bulletin explains that property-damage liability insurance covers damage an at-fault driver causes to other people’s vehicles or property.
Putting the car accident claim adjuster timeline Virginia claims follow together shows one pattern. The evaluation, the medical records and the legal deadlines each move on their own track. Understanding each one helps a reader plan.
Quick answers
How long does the car accident claim adjuster timeline Virginia uses take?
Virginia sets no fixed period. The pace depends on records, treatment status and the number of parties.
Does a pending insurance claim stop the lawsuit deadline?
No. The statute sets the deadline, and an open claim file does not change it.
Can an adjuster set the value of a car accident claim?
An insurance adjuster’s evaluation is one view of a claim, and what a claim is worth depends on the facts of each case.