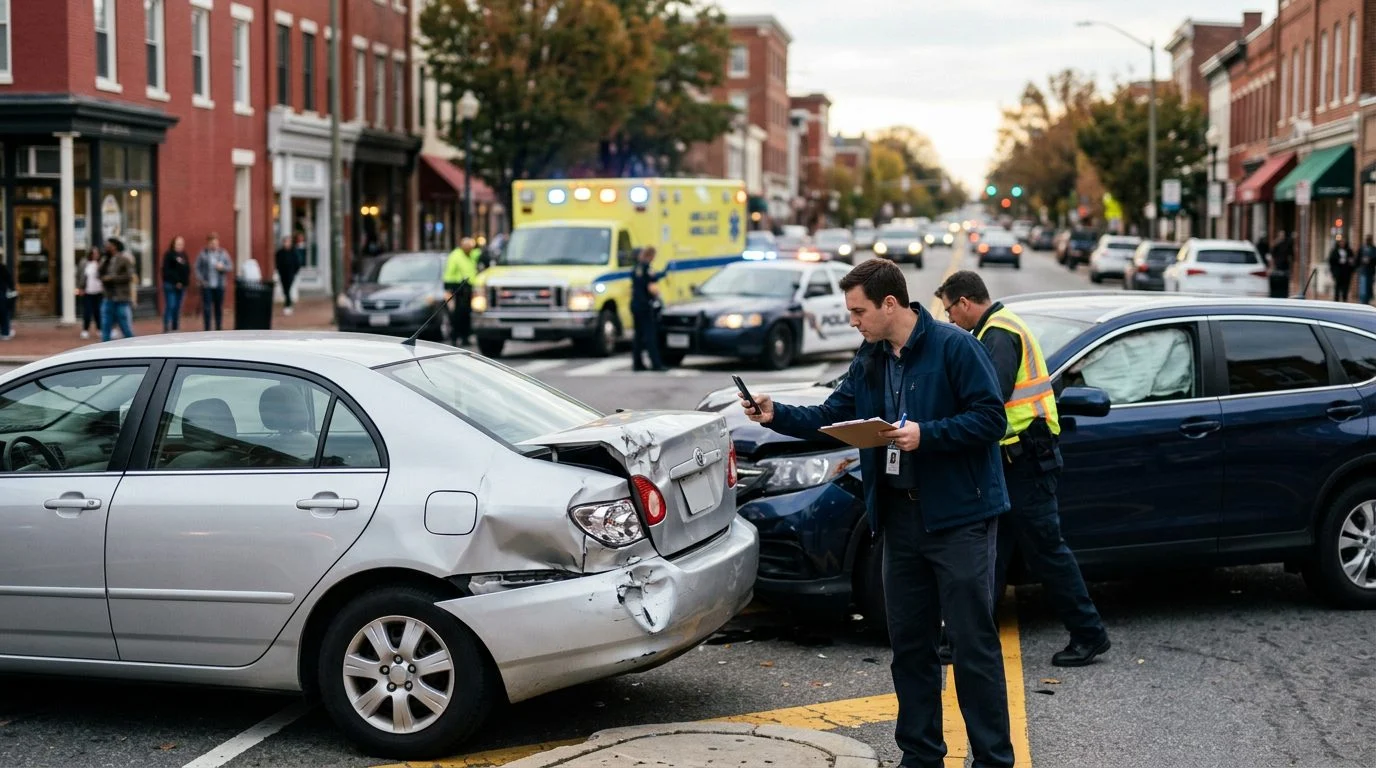
Dealing With an Insurance Adjuster After a Virginia Car Accident
Calls, forms and early offers can arrive quickly after a crash. Knowing what the adjuster is asking for can help you decide what to say, what to sign and when.
Published November 9, 2026
You were hurt in a car crash, and an insurance adjuster has started asking for records. You want to know how long this will take. The honest answer is that the pace depends on your facts, your injuries and how fast the paperwork arrives.
This page explains how an insurance adjuster handles a car accident injury claim in Virginia. It covers what the adjuster reviews, what slows the work down, and how the insurance claim relates to the deadline for a lawsuit.
How long do insurance adjusters typically take to evaluate and respond to a car accident injury claim in Virginia?
There is no single timeline for every claim. An adjuster’s pace depends on the crash, the injuries and how quickly the records come in.
Most claims move through a few stages. The first is initial contact, when the adjuster confirms the crash and who was involved. Next comes gathering documents, then evaluating the injury, and finally a response.
Each stage can run longer while information is still arriving. This is most common when treatment is ongoing. An adjuster usually wants to understand the full extent of the injuries before judging them, and a person who is still healing may not yet know the final picture.
Pace also changes as the file grows. A claim with complete records and no dispute about fault often moves more steadily than one with missing bills or conflicting accounts of the crash. It helps to ask the adjuster what they still need. A clear list of open items makes the next step easier to see.
If you were hurt in a Virginia car crash and an adjuster is already asking questions, you may have a claim, and you don't have to sort through the process alone. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
What does an insurance adjuster review during a car accident injury claim?
An adjuster usually reviews the crash report, photos, vehicle damage estimates, medical records and bills, and records of lost work time.
The police report is often one of the first records requested. Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894).
Adjusters also separate two kinds of claims. A property damage claim covers the vehicle and personal items. A bodily injury claim covers the person’s injuries, including death resulting from bodily injury. The injury claim usually rests on medical records, because the adjuster needs proof of the diagnosis, the treatment and the bills.
Policy limits matter too. For motor vehicle owner’s policies effective on or after January 1, 2025, Virginia sets minimum bodily injury liability limits of $50,000 for one person in any one accident and $100,000 for two or more persons. The minimum property damage limit is $25,000 (Va. Code § 46.2-472). These are minimums. Some policies carry higher limits, so the adjuster will check what the policy actually provides.
What can slow down an adjuster’s response to an injury claim?
The most common slowdowns are ongoing treatment, missing records and disputes about how the crash happened.
- Ongoing treatment. Until the injuries are better understood, an adjuster may wait before valuing the injury claim.
- Missing or late paperwork. A medical bill that arrives months after the visit can hold up the file. So can a wage record that isn’t finished.
- Disputed fault. When the drivers tell different stories, the adjuster may take witness statements or ask outside experts for an accident reconstruction. These reviews take time.
- Coverage questions. Virginia policies generally must include uninsured motorist coverage and underinsured motorist coverage (Va. Code § 38.2-2206). If the at-fault driver’s coverage is low or unknown, the adjuster may need to confirm which policies apply before responding.
How does the two-year filing deadline relate to an insurance claim in Virginia?
The insurance claim and the lawsuit deadline run on separate tracks. The lawsuit clock starts at the injury, not when the insurer responds.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions.
A long insurance review uses time from that same clock. Some claims carry notice requirements that run out sooner than the filing deadline. Write down the crash date and the injury date so you can track every deadline. For the start date rule, see Va. Code § 8.01-230.
What should someone keep track of while an insurance claim is pending?
Keep a dated log of every contact, copies of every record and notes on how the injuries affect daily life.
Start with a log. Write down each phone conversation, letter and email with the adjuster. Note the date, the person’s name and what was said.
Next, keep copies. Save medical records, bills, pay stubs and receipts for out-of-pocket expenses tied to the crash. Keep them in one folder you can find quickly.
Then track daily life. Write down missed work, tasks you can’t do, pain you feel and appointments you attend. Adjusters often ask how injuries affect work and home life as the claim develops.
These records help the claim move forward and show where it stands. They also keep your own facts in view, because what applies to you depends on those facts.
Frequently asked questions
How long does an insurance adjuster take to respond to a car accident injury claim in Virginia?
There is no set number of days. The pace depends on the crash, the injuries and how fast the records arrive.
Does an insurance claim stop the two-year deadline to file a lawsuit in Virginia?
No. The two-year period generally runs from the date of injury, so a pending insurance claim does not stop it.