Car Accidents | Virginia
Car Insurance Doesn't Cover Everything: What Virginia Drivers Should Know
A plain-language guide to the losses a standard auto policy may leave out after a crash, and why the wording of your own policy matters.
Published November 15, 2026
A crash can leave you with a damaged car, medical bills and missed work.
A crash can leave you facing bills and losses that your insurance may not fully cover. In short, most policies leave out some losses, including wear and mechanical problems, personal belongings, costs above policy limits, and damage that falls under a coverage you did not buy. The exact answer depends on the policy wording, so it helps to know how the coverages fit together.
How Car Insurance Is Divided Into Coverage Types
Car insurance is made of separate coverages, and each one pays for a different kind of loss.
Liability coverage pays for injury and property damage that the policyholder causes to other people. It does not repair the policyholder’s own car or cover the policyholder’s own injuries. Those losses fall under first-party coverages: collision, comprehensive, medical payments and uninsured motorist coverage. A policy pays for them only if it includes them.
Virginia sets minimum liability limits. For owner’s policies effective on or after January 1, 2025, the state requires at least $50,000 for injury or death of one person in one accident, $100,000 for two or more people, and $25,000 for property damage (Va. Code § 46.2-472). Those are the minimums, not a measure of what a serious crash can cost.
The declarations page is the first place to look. It lists your coverages, limits and deductibles. The policy wording controls the final answer, so read the full policy, not only the summary.
These Virginia rules apply the same way to drivers in Winchester, Harrisonburg, Richmond, Henrico County and across the Shenandoah Valley.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Damage to Your Own Car That Collision and Comprehensive May Not Pay
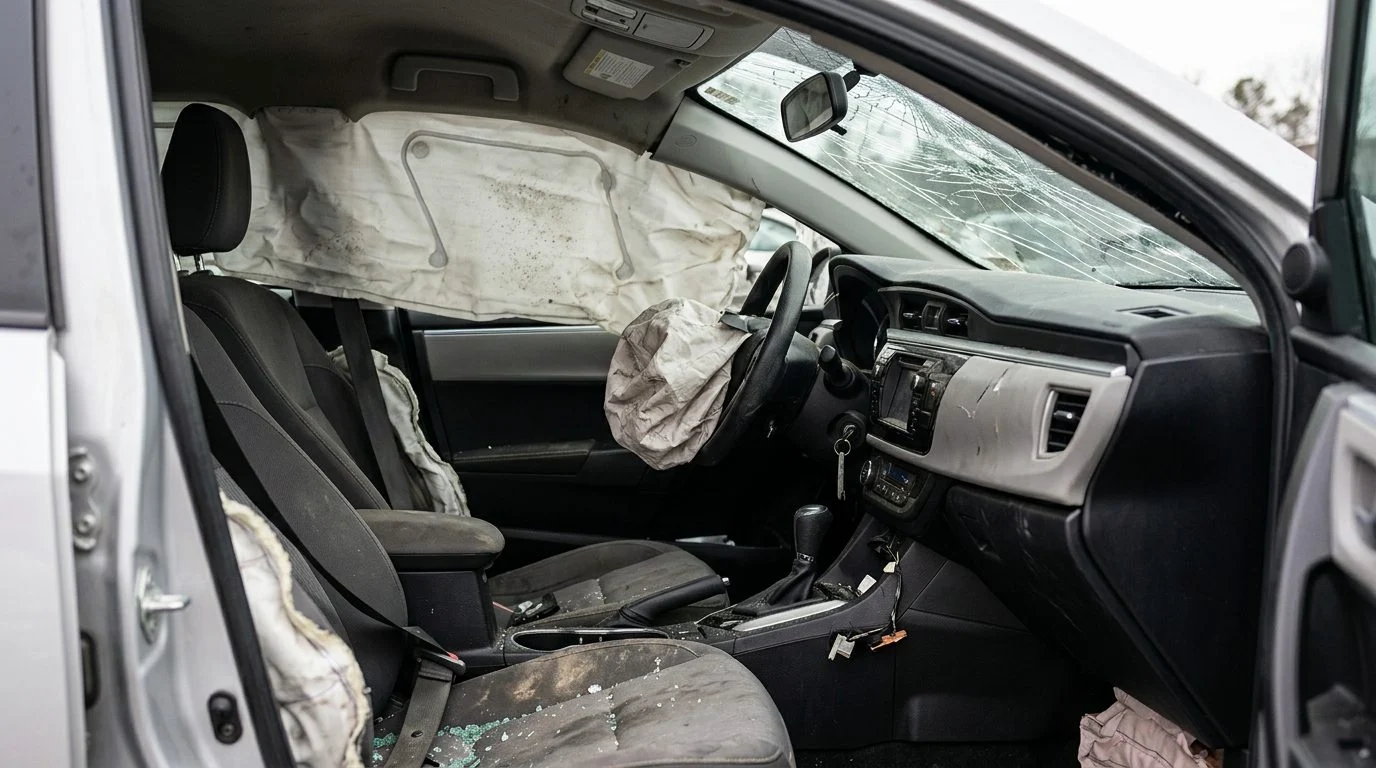
Collision and comprehensive coverage are the main ways a policy pays for damage to your own car. Without them, the repair bill usually stays with you.
Collision covers damage from a crash with another vehicle or an object, such as a guardrail or utility pole. Comprehensive covers many non-crash events, including theft, hail, fire, falling objects and animal strikes. A loss not listed in the policy’s wording may not be covered.
Deductibles add another gap. You usually pay the deductible first, so a small repair may fall almost entirely on the owner.
Wear and tear, rust, mechanical breakdown and gradual deterioration are commonly excluded from both coverages. A part that failed on its own is different from damage caused by a crash, and the cause often decides the claim.
Modifications and aftermarket equipment, such as custom wheels, stereos or lift kits, may be excluded unless the policy lists them. Owners of older cars sometimes drop collision coverage to lower premiums. If they do, crash damage to their own car is not paid by the policy.
Read the exclusions section of the policy itself. General summaries vary from insurer to insurer, and the policy wording is what applies.
Losses Above Policy Limits and Other Coverage Gaps
Liability limits are the ceiling on what a policy pays for harm the policyholder causes.
Liability limits set the most the insurer will pay for injury or property damage the policyholder causes. A crash that injures several people or damages expensive property can exceed those limits quickly.
Liability limits also apply per accident. If several people are hurt, they share the same per-accident limit, which can leave less for each person.
When a car is totaled, many policies pay its actual cash value, meaning its value just before the crash. That figure can be less than the cost of buying a comparable car today.
Confirm your limits in writing, and review them whenever you change coverage.
Personal Belongings, Rental Costs and Lost Use of the Vehicle
Personal items inside a car are often not covered by an auto policy.
Phones, laptops, clothing, tools and other belongings usually fall outside collision and comprehensive coverage. A homeowners or renters policy may cover some of these items, so check that policy too.
Rental car reimbursement is usually an optional add-on. Without it, the cost of a rental while your car is in the shop may not be paid by your own policy.
Virginia law also addresses loss of use directly. A person who can recover for damage to a vehicle may recover the reasonable cost actually incurred to rent a comparable substitute vehicle, for a reasonable repair period or, if the car is a total loss, a reasonable time to buy a new one. That person still has a duty to mitigate damages, meaning the person must try to keep those costs reasonable (Va. Code § 8.01-66).
If an insurer fails to provide a comparable substitute vehicle, and a judge later finds that failure was not in good faith, the insurer is liable for $500 or double the rental cost, whichever is greater (Va. Code § 8.01-66).
Towing and storage may be limited or excluded, depending on the roadside and additional coverages in the policy. Trailers, custom equipment and cargo carried for work are often excluded or need separate coverage.
Injuries and Losses Covered Only by Optional or Uninsured Coverages
Some injury costs are covered only when a specific optional coverage is on the policy.
Medical payments coverage, where a policy includes it, pays certain medical expenses for the policyholder and passengers, up to its limit. Not every policy includes it, and the limit may be small compared with a hospital stay.
Virginia law sets rules for uninsured motorist coverage. Under Va. Code § 38.2-2206, a Virginia motor vehicle liability policy must include an endorsement to pay the insured the sums the insured is legally entitled to recover from an uninsured motorist. That section also requires underinsured coverage with limits equal to the uninsured limits. Va. Code § 38.2-2206 reads: “The endorsement shall provide that underinsured motorist coverage shall be paid without any credit for the bodily injury and property damage coverage available for payment, unless any one named insured signs an election to reduce any underinsured motorist coverage payments by the bodily injury liability or property damage liability coverage available for payment by notifying the insurer as provided in subsection C of § 38.2-2202.”
Uninsured limits equal, but do not exceed, the policy’s liability limits, unless a named insured rejects the additional uninsured coverage by notifying the insurer. This matters when the at-fault driver has no insurance or too little.
Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894).
When the other driver cannot be identified, the question becomes which coverage applies. Uninsured motorist coverage is often the first coverage to review in that situation.
When a Commercial Vehicle or Work Use Changes the Coverage Picture
A personal auto policy may not respond the same way when a business vehicle is involved in a crash.
Vehicles owned by a business or used for work are usually insured under commercial policies with different limits and exclusions. Who owned the vehicle, who was driving and whose policy applies all shape the claim.
Federal rules also set financial responsibility levels for many motor carriers. Under 49 U.S.C. § 31139, the Secretary of Transportation must prescribe regulations setting minimum levels of financial responsibility, covering public liability, property damage and environmental restoration, for certain transportation of property by motor carriers and motor private carriers between a place in a State and other places the section lists.
A crash can involve more than one negligent party.
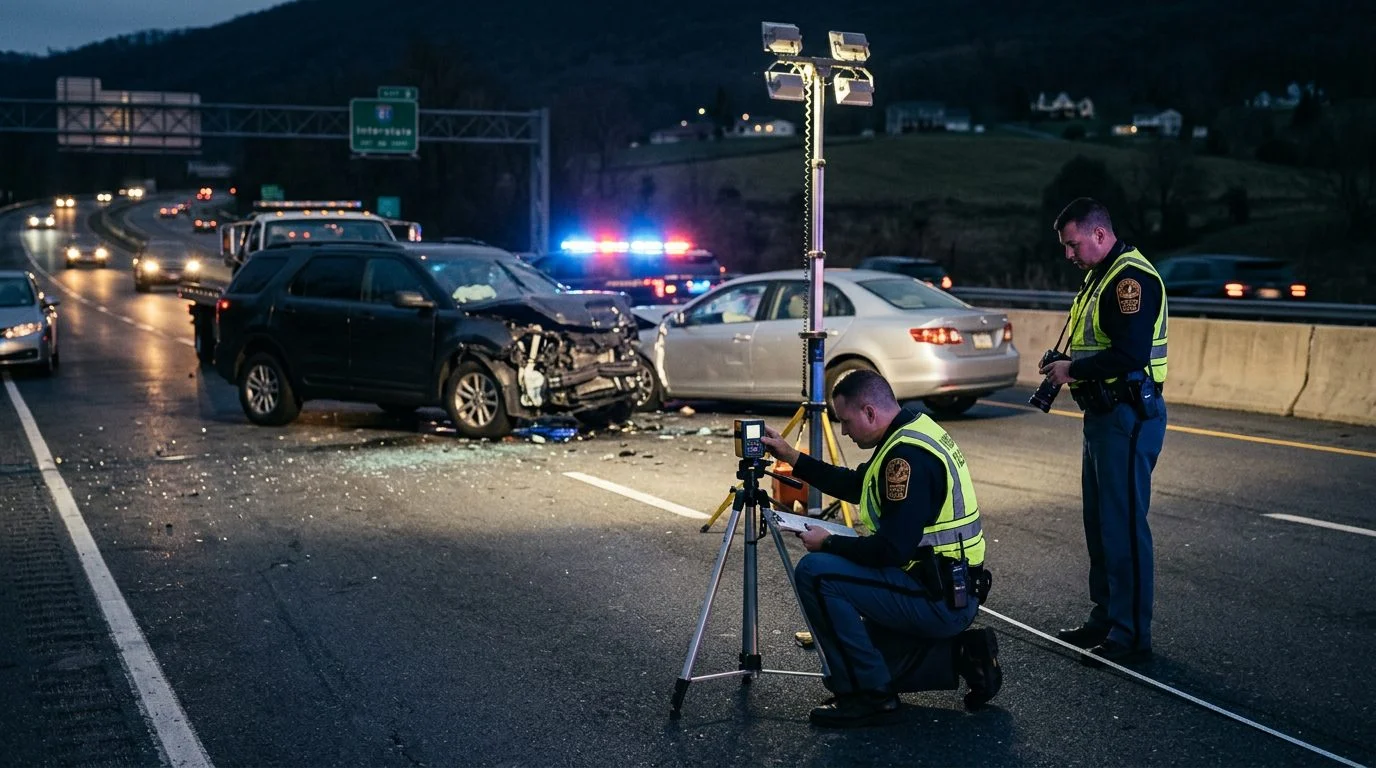
Write down the other vehicle’s owner, the driver’s name, and any insurance details exchanged at the scene. Photos of the damage and the vehicles’ positions also help sort out which policy applies. For more on truck crashes, see truck accidents.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
When Insurance Does Not Cover a Loss: Other Steps and Deadlines
A loss your own policy excludes may still be pursued against the at-fault driver or owner, depending on the facts.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions.
Review the declarations page, endorsements and any denial letter. Together they show which damage the policy excludes and the reason given.
Common questions
Does car insurance pay to repair my own car?
Only if the policy includes collision or comprehensive coverage that applies to the loss. Without them, the repair bill usually stays with the owner.
Is personal property stolen from a car covered?
Usually not under an auto policy. A homeowners or renters policy may cover some personal items instead.
Does comprehensive coverage cover everything?
No. It covers the non-crash events listed in the policy, and the wording decides the answer.