Virginia Car and Truck Accident Claims
What Not to Tell an Insurance Adjuster in Virginia
An adjuster's call can feel routine, but what you say can shape your claim. Correll Law Firm helps injured people from Winchester, Harrisonburg, Front Royal, the Shenandoah Valley, Richmond and Henrico County understand their options.
Published October 28, 2026
What not to tell an insurance adjuster? Avoid guessing about the crash, admitting any fault, and calling your injuries minor. The adjuster works for the insurance company, and what you say can become part of the claim file.
This guide explains the most common problem statements and what you can say instead. It covers general Virginia rules, so your own facts may change the picture.
Why What You Say to an Insurance Adjuster Matters
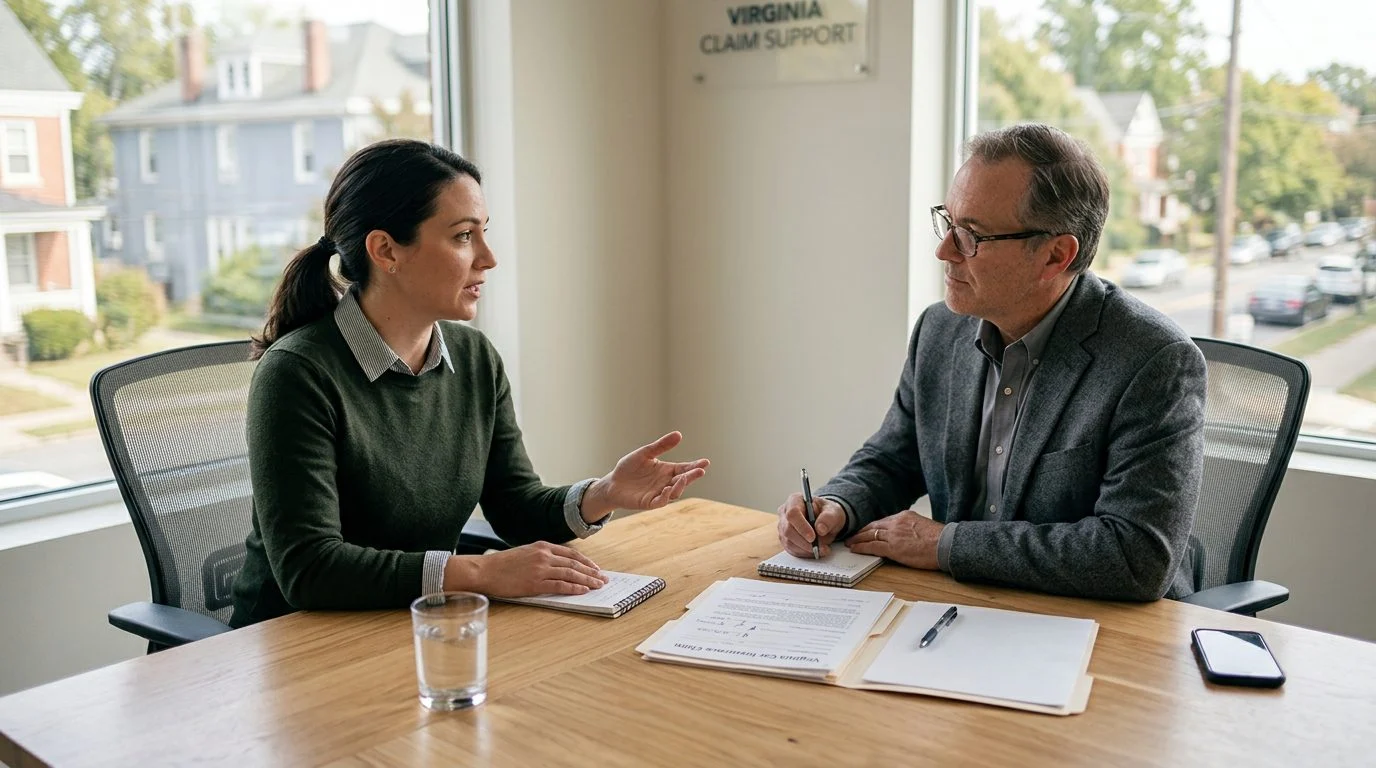
An insurance adjuster evaluates your claim for the insurer. Consumers with questions about an insurance company or agent can file a complaint with the Virginia Bureau of Insurance, part of the State Corporation Commission. The adjuster is not there to represent you.
Your words matter because they can become part of the claim file. An adjuster may write down what you said, and that note can be quoted back later, sometimes months after the crash. A friendly tone does not change the purpose of the call. The adjuster is still gathering information for the insurer. Knowing what not to tell an insurance adjuster starts with that fact. Keep answers short, accurate, and limited to what you know.
If a crash has left you or a family member fielding calls from an insurance adjuster, you do not have to sort through it alone, and the firm is glad to talk through your situation. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Do Not Guess or Admit Fault
Do not guess how the crash happened, and do not say you were at fault. A guess can create a record that does not match the facts later. Speed, distance, and who had the green light are common topics where people estimate. Say what you saw and felt, not what you think the other driver did.
Speed comes up often in these calls. The Insurance Institute for Highway Safety reports that speeding increases crash risk and the severity of resulting injuries. Avoid giving speed numbers you are not sure of.
Polite words can be read as admissions. “I’m sorry” is a normal human reaction, but an adjuster may read it as an admission of fault. Describe what happened without blaming yourself or anyone else.
Virginia follows contributory negligence: if you are found even partly at fault, you may be barred from recovering, with limited exceptions. Talk to a lawyer about your facts.
Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894). The duty to stop is set out in Va. Code § 46.2-894. The two-year period discussed later in this guide is the deadline to file a lawsuit, not the deadline to report a crash.
Do Not Describe Your Injuries as Minor or Final
Do not call your injuries minor or finished before a medical evaluation is complete. Saying “I’m fine” or “it’s just a bruise” on an early call can conflict with symptoms that appear hours or days later. Many people feel unsure how hurt they are right after a crash, and that uncertainty is normal.
Describe your current symptoms accurately. If your medical care is still going on, say so. Tell the adjuster which symptoms you have now and which ones you are still watching. Do not try to predict how long recovery will take. A diagnosis, a treatment plan, or a recovery timeline should come from your treating providers, not from a guess on a phone call.
If the adjuster asks about past health problems, you can say you will provide relevant records through the proper channels. Summarizing old conditions from memory often leaves out details. Those gaps can later look like contradictions, even when they were honest mistakes.
Handling a Recorded Statement Request
Before you agree to a recorded statement, ask what it is for and which topics it will cover. A clear answer helps you decide how to prepare. You can also ask for questions in writing or for time to review them before you respond.
During the statement, stick to facts you know personally. Say “I don’t know” or “I don’t remember” when that is true. Avoid estimates presented as certainties, and do not guess at what someone else intended or did.
If the crash involved a company vehicle or a work assignment, expect questions about job duties, routes, and schedules. Those answers can affect how the claim is reviewed. The firm’s pages on work van accidents and delivery truck accidents explain these situations in more detail.
Social Media, Photos, and Daily Activity
Adjusters may review public posts, photos, check-ins, and comments. Content about an activity can be read out of context. A photo from a family outing may be used to question how hurt you are, even if it shows only a few minutes of activity.
Avoid posting about the crash, your injuries, or the insurance claim while the claim is open. Ask family members and friends not to tag you in such posts. Changing your privacy settings is reasonable, but it does not replace careful posting.
An ordinary day, like a short walk or a family dinner, does not necessarily contradict an injury. Adjusters may still draw conclusions from it. Keep your own notes about what the day actually required, including any pain that followed.
Responding to a First Settlement Offer
You do not have to accept a first settlement offer on the spot. Ask the insurer to explain the basis for the offer in writing. A first offer may come before the full medical picture is known, including how long symptoms last or whether more treatment is needed.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions. Section 8.01-243(A) provides that, unless otherwise provided in that section or by other statute, every action for personal injuries, whatever the theory of recovery, shall be brought within two years after the cause of action accrues.
Narrow pauses can apply. For example, Va. Code § 8.01-229 does not count the time a criminal prosecution arising from the same facts is pending toward the civil deadline. Track key dates in writing rather than assuming a pause applies.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
When a Claim Is Denied and What to Keep
Read a denial letter closely and keep a dated file of everything about the claim. Note the reasons given, any deadlines, and any requests for more information. Answer requests in writing when you can, and keep copies of what you send.
Your file can include medical records, bills, photos of the vehicles and the scene, the police report number, and written communications with the insurer. Write down the date and time of each call, the adjuster’s name, and what was said. Notes made close to the event are easier to rely on later. If you believe an insurer has treated you unfairly, the Virginia Bureau of Insurance explains how to file an insurance complaint.
Families of people killed in crashes face a different timeline. A Virginia wrongful death action is filed by the decedent’s personal representative within two years of the death (Va. Code §§ 8.01-50(C), 8.01-244(B)), on behalf of the family members the statute protects. The limitation is in Va. Code § 8.01-244. The statute also describes who shares in the award, in Va. Code § 8.01-53. The firm’s pages on car accident claims in Virginia and wrongful death give more context.
Frequently Asked Questions
What should I say to an insurance adjuster?
Stick to facts you know, describe current symptoms accurately, and say “I don’t know” when that is true.
Do I have to accept an insurance adjuster’s offer?
No. You can ask for the basis of the offer in writing and take time to review it.
What not to tell an insurance adjuster, in short?
Do not guess about the crash, do not admit fault, and do not call your injuries minor before a medical evaluation is complete.