Who Covers X-Rays After a Commercial Vehicle Crash?
Imaging and other medical bills after a truck or commercial vehicle crash can come from more than one source. Here is how to think through where they may be covered.
Published October 31, 2026
If you’re asking who covers X-rays after a commercial vehicle crash, the short answer is that more than one source may pay. Your own health insurance often comes first. The at-fault party’s liability insurance or the commercial vehicle owner’s policy may come into play later. Which source applies depends on the facts of the crash.
Who Usually Pays for X-Rays After a Commercial Vehicle Crash in Virginia
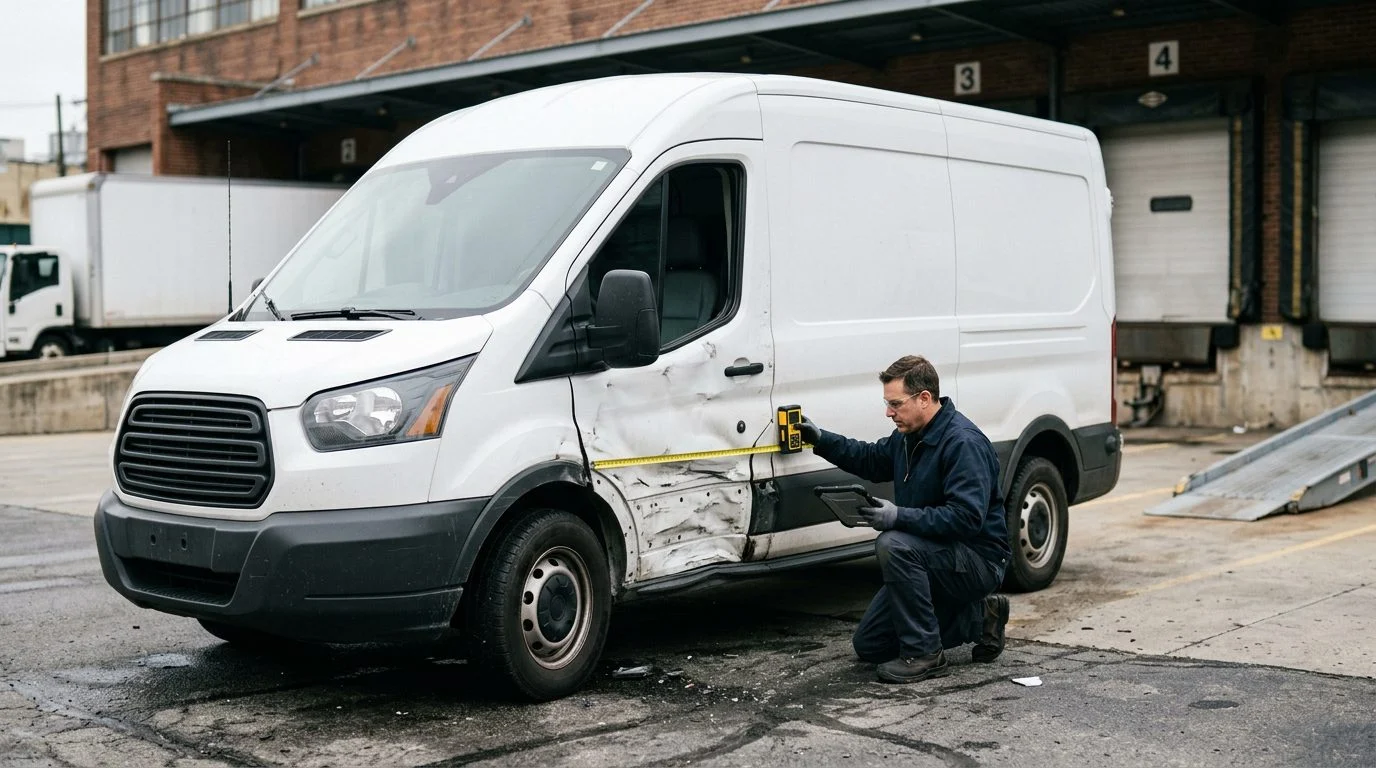
The answer to who covers X-rays after a commercial vehicle crash has three parts. Imaging bills may be paid by the injured person’s health plan, the at-fault driver’s liability insurance, or the owner’s policy on the commercial vehicle.
Each source works in its own way. Your health plan pays under its own terms. Those terms set which providers are in network, what needs approval, and what the plan covers. Liability insurance responds to a claim against the person whose driving caused the crash. That claim has to be made before it can pay out.
A bill can be paid by one source first and sorted out with another later. Bills from the same visit may come from a hospital, a radiology group and a separate physician. Each may send its own bill. Keeping the records together makes it easier to see who paid what.
If a commercial vehicle crash has left you with imaging bills and open questions, you do not have to sort them out alone. The firm is ready to talk through your situation. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Why Imaging Is Ordered After a Truck, Bus or Van Crash
Imaging is ordered to look for injuries that are not visible at the scene. Emergency staff often start with X-rays to check for broken bones. If the picture does not show the whole problem, a doctor may order a CT scan or an MRI.
The choice of imaging depends on your symptoms and the treating physician’s judgment. Symptoms can change in the hours and days after a crash. That is why the first medical visit matters, and why you should tell providers exactly where you hurt and when the pain started.
Coverage questions often turn on the medical record. Imaging ordered soon after the crash, for symptoms reported at the time, is easier to connect to the crash. Imaging ordered weeks later, with no record of symptoms, is harder to connect. For the broader picture of how these claims work, see the firm’s commercial vehicle accident guide.
Your Own Health Insurance and How It Applies
Your health plan may cover emergency imaging under its own terms. Those terms can include network rules, referral needs and approval steps. The plan’s explanation of benefits shows what was billed, what was paid and what is still open, so keep every one.
Virginia has a specific rule for in-network providers. Va. Code § 8.01-27.5 defines a “health care policy” as any health care plan, subscription contract, evidence of coverage, certificate, or similar arrangement offered by a health insurer to cover all or part of the cost of covered health care services (Va. Code § 8.01-27.5).
Insurance from a separate source is treated differently from a liability claim. In plain terms, your health plan and a liability claim can run on separate tracks.
The At-Fault Driver’s Liability Insurance
The at-fault driver’s liability insurance is the source tied to the crash itself. The Insurance Information Institute explains that liability insurance covers the other party when the policyholder is at fault.
A claim is presented to the at-fault driver’s insurer, which can then ask for medical records. Those requests often include imaging reports. An adjuster may ask for the complete imaging file, not just a summary. Medical records that link the X-rays to the crash support the claim.
Adjusters work for the insurer. It helps to keep copies of everything you send and everything you receive. Write down the dates of calls and the names of the people you spoke with.
The Commercial Vehicle Owner’s Policy and Federal Insurance Rules
Federal rules require motor carriers to hold minimum financial responsibility before they operate. Under 49 C.F.R. § 387.7(a), a motor carrier may not operate a motor vehicle until it has obtained and has in effect the minimum levels set in § 387.9.
The required amounts vary by the type of operation and the cargo. The federal schedule in 49 C.F.R. § 387.9 lists $750,000 for for-hire carriage of nonhazardous property in interstate or foreign commerce, at a gross vehicle weight rating of 10,001 pounds or more. Other categories carry different minimums, including $1,000,000 and $5,000,000.
Insurance policies for private vehicle owners can have different coverage limits, so the policy involved in a crash is worth reviewing. For policies effective on or after January 1, 2025, the owner’s policy must cover $50,000 for bodily injury or death of one person in one accident (Va. Code § 46.2-472(B)). A commercial carrier’s coverage can be larger than that.
Carriers must keep proof of this coverage at their principal place of business (49 C.F.R. § 387.7(d)). That proof is public information. A member of the public may request it for review (49 C.F.R. § 387.7(e)(1)).
Identifying Each Source: Reports, Records and Deadlines
The crash report and the driver’s information are the starting points for finding each coverage source. Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894).
These details help trace the vehicle, its owner and its insurer. The carrier’s name on the vehicle is another useful clue.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions. The two-year period is the deadline to file a lawsuit, not to report a crash (Va. Code § 8.01-243). Some claims carry notice requirements that run out sooner, so gather imaging bills and records early.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
How Imaging Bills Fit Into a Claim and How the Firm Can Be Reached
Keeping every imaging report, bill and insurer explanation makes a claim easier to follow. A simple folder sorted by date and provider shows what was billed, what was paid and what is still open.
Correll Law Firm handles car accidents, truck accidents, commercial vehicle accidents, catastrophic injuries, traumatic brain injury, spinal cord injury and wrongful death. The firm has offices in Harrisonburg and Winchester. It serves people across the Shenandoah Valley, and in Richmond and Henrico County.
Quick Answers
Who covers X-rays after a commercial vehicle crash?
More than one source may. The injured person’s health plan, the at-fault driver’s liability insurance and the carrier’s policy are the main places to look.
Does a trucking company’s insurance cover X-rays?
It may, if the company or its driver is at fault and the claim is presented to its insurer.
Should I keep my imaging records?
Yes. Reports, bills and insurer statements show what was billed and what has been paid.