Virginia Crash Claims
What Is an Insurance Adjuster? What to Know After a Virginia Crash
An adjuster works for the insurance company, not for you. Learn what that role means before you give a statement or sign anything after a crash.
Published October 28, 2026
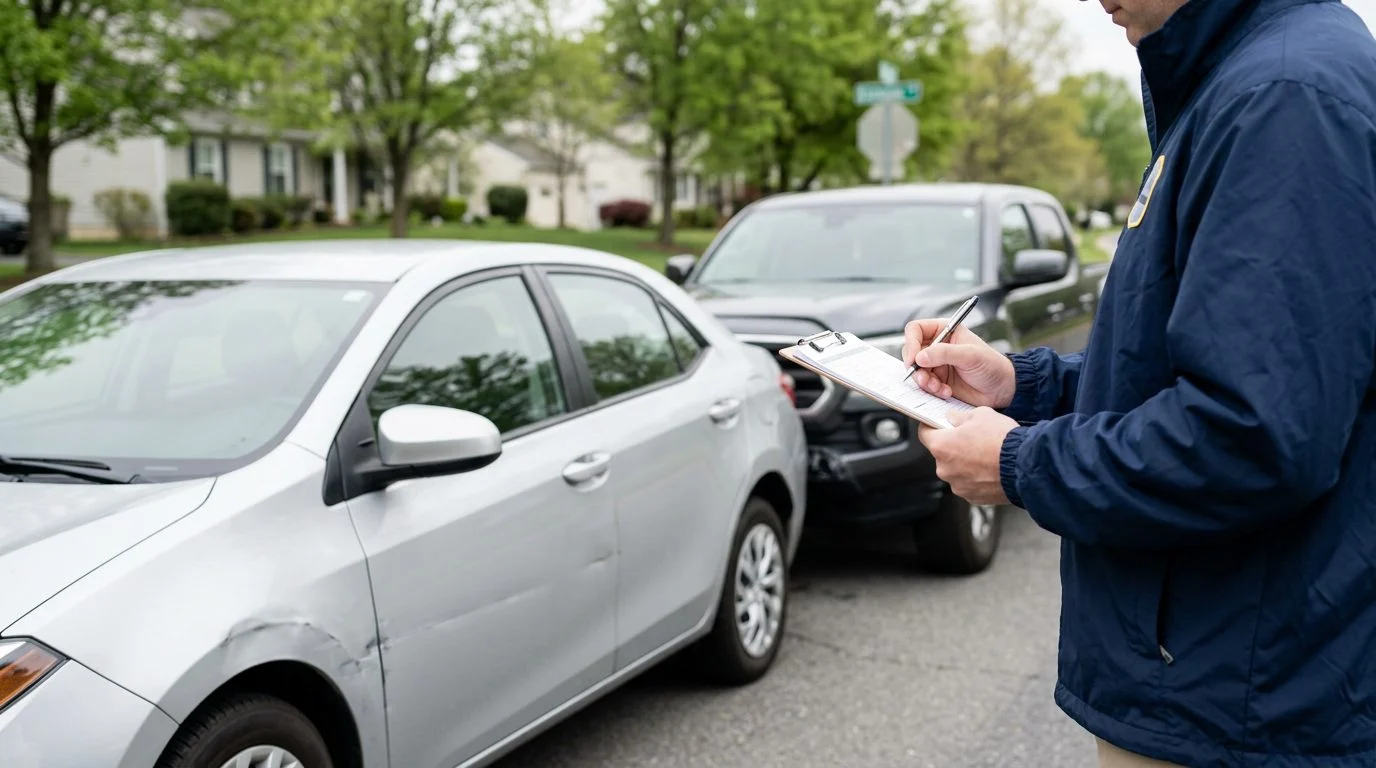
An insurance adjuster is the person an insurance company assigns to investigate a claim, decide what the insurer may owe, and report back. After a car or commercial vehicle crash in Virginia, an adjuster is often one of the first people an injured person hears from. This page answers the question, what is an insurance adjuster, and explains what the role means for you.
What an insurance adjuster does
An insurance adjuster investigates a claim for the insurer and reports what the policy may cover. The adjuster works for the insurance company, not for the person who filed the claim.
To do this, the adjuster reviews the claim file, the policy language, the loss as reported, and any documents submitted. The adjuster looks at what happened, what was damaged, and what injuries are being claimed.
That work matters in a crash claim. The adjuster’s findings often shape the insurer’s first offer. An adjuster’s report is the insurer’s internal position. It is not a court ruling, and it does not decide what a judge or jury would find.
Adjusters are not the injured person’s representative. Their job is to measure the insurer’s exposure, meaning how much the company may have to pay. Keep that in mind when you read letters or listen to phone calls.
If an insurance adjuster has contacted you after a Virginia crash, you do not have to sort it out alone, and the firm is ready to talk through your situation. Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Types of insurance adjusters
Company adjusters are employees of one insurance company. They handle claims that company receives, and they usually work under its guidelines and authority limits.
Independent adjusters are hired on assignment. An insurer may send them a claim, and they may take assignments from several companies. Their authority and reporting lines depend on each assignment.
Both types investigate, document and recommend. The difference is who employs them and how much decision authority they hold on a given file. Knowing which company an adjuster works for tells you whose file it is.
Commercial vehicle losses may go to adjusters who handle larger or multi-party claims. One truck crash can involve the driver’s insurer, the carrier’s insurer, and coverage for the vehicle owner or cargo. Each may assign its own adjuster, so the file can have more than one voice.
How an insurance adjuster works a claim
An adjuster usually works a claim in four steps. The details vary by insurer and by claim.
First, the claim is reported and assigned. The adjuster opens a file and makes first contact with the people involved.
Second, the adjuster requests information. That may include the crash report, photographs, repair estimates and medical records.
Third, the adjuster reviews coverage, fault and damages, then writes down the findings.
Fourth, the adjuster states a position. The adjuster may ask for more records, make an offer, or deny all or part of the claim.
Virginia law also addresses insurers that deny or fail to pay certain motor vehicle claims.
Adjusters often handle many files at once, so response times and follow-up vary. A slow reply does not always mean a claim is stalled, and a fast reply does not always mean the claim is fair.
Investigating the accident and reviewing injuries and property damage
Adjusters start with the facts of the crash. They gather scene evidence, photographs, witness statements and the police crash report. Those records often set the timeline for the rest of the claim.
Crash reporting is a driver’s duty. Virginia requires a driver involved in a crash with injury or death to stop and report it to police immediately (Va. Code §§ 46.2-371, 46.2-894). This reporting duty is separate from any lawsuit deadline.
For vehicle damage, adjusters review repair estimates, decide whether a vehicle is a total loss, and may inspect the vehicles themselves.
For injuries, adjusters look at medical records, the treatment history, and whether the treatment links to the crash. They may also ask outside medical reviewers or accident reconstruction analysts for technical input. This review can take time, and it can change as new records arrive.
Deciding who is at fault
Liability decisions rest on the evidence the adjuster gathers. That includes the crash report, statements and physical evidence. Adjusters may place fault on one driver or on several.
Fault works differently in an insurance file than in court. Virginia follows contributory negligence: if you are found even partly at fault, you may be barred from recovering, with limited exceptions. Talk to a lawyer about your facts.
An adjuster’s fault assessment is the insurer’s position. It is not a final answer. Fault decisions can be disputed, and you may wish to ask the adjuster for the reasons behind any finding.
Making an offer and what it does and does not decide
A settlement offer is the insurer’s proposal to resolve a claim for a stated amount. Insurers often ask the injured person to sign a release in exchange.
An offer can be accepted, countered or rejected. Read any release carefully before you sign it. Ask exactly what it covers.
Under Va. Code § 8.01-35.1, when a release or covenant not to sue is given in good faith to one of several people liable for the same injury or wrongful death, it does not discharge any other person from liability unless its terms so provide. The wording matters.
An offer is not a promise about how the claim will end.
Virginia generally allows two years from the date of injury to file a personal injury lawsuit (Va. Code § 8.01-243(A)); the clock runs from the date of injury, not the date of discovery, with narrow exceptions.
Not sure what your next step is?
Talk it through with Correll Law Firm — we can walk you through how a situation like yours is usually handled and what your options are.
Talking with an adjuster: what to know before speaking
Adjusters may ask for a recorded statement. You may wish to ask what the statement is for and think about your answers before you give one.
Stick to facts you know. Avoid guessing about speed, fault, injuries or future medical needs. A guess can be repeated back to you later as if it were a fact.
Keep copies of letters, estimates, medical bills and the claim number. Write down the date and name of each call.
Your own auto insurance policy may also play a role after a crash.
Remember that the adjuster works for the insurer. A person may wish to speak with a lawyer about the claim before accepting an offer or signing a release.
Adjusters in commercial vehicle and truck claims
Commercial vehicle crashes can involve several insurers, employers and policy layers. That can make the adjuster’s role more complex.
Work vans, delivery trucks and buses each involve different coverage and records. A claim may move through different adjusters and departments as the file grows.
For an overview of the claim process after a commercial crash, read the commercial vehicle accidents guide. For vehicle-specific details, see the pages on work van accidents, delivery truck accidents, and bus accidents.
Is an adjuster the same as a lawyer?
No. An adjuster works for the insurer, while a lawyer represents the injured person.
Who decides fault in a crash claim?
The adjuster’s fault finding is the insurer’s position. A judge or jury decides fault in a lawsuit.
Should I give a recorded statement?
You may wish to ask what it is for and review your records first.
Related practice areas
- Commercial Vehicle Accidents in Virginia: What Injured People and Families Should Know First
- Work Van Accident Lawyer in Virginia: Crashes Involving Work Vans and Delivery Vehicles
- Delivery Truck and Box Truck Accident Lawyer Serving Richmond and Henrico County
- Bus Accident Lawyer in Virginia: Injuries From Crashes With Buses and Passenger Vehicles